Ask it about the house: yes. School fees: yes. Retirement: yes. Four right answers that add up to a no.
Can it tell you…
Your appsApps
Rivu
What one goal needs each month
✓
✓
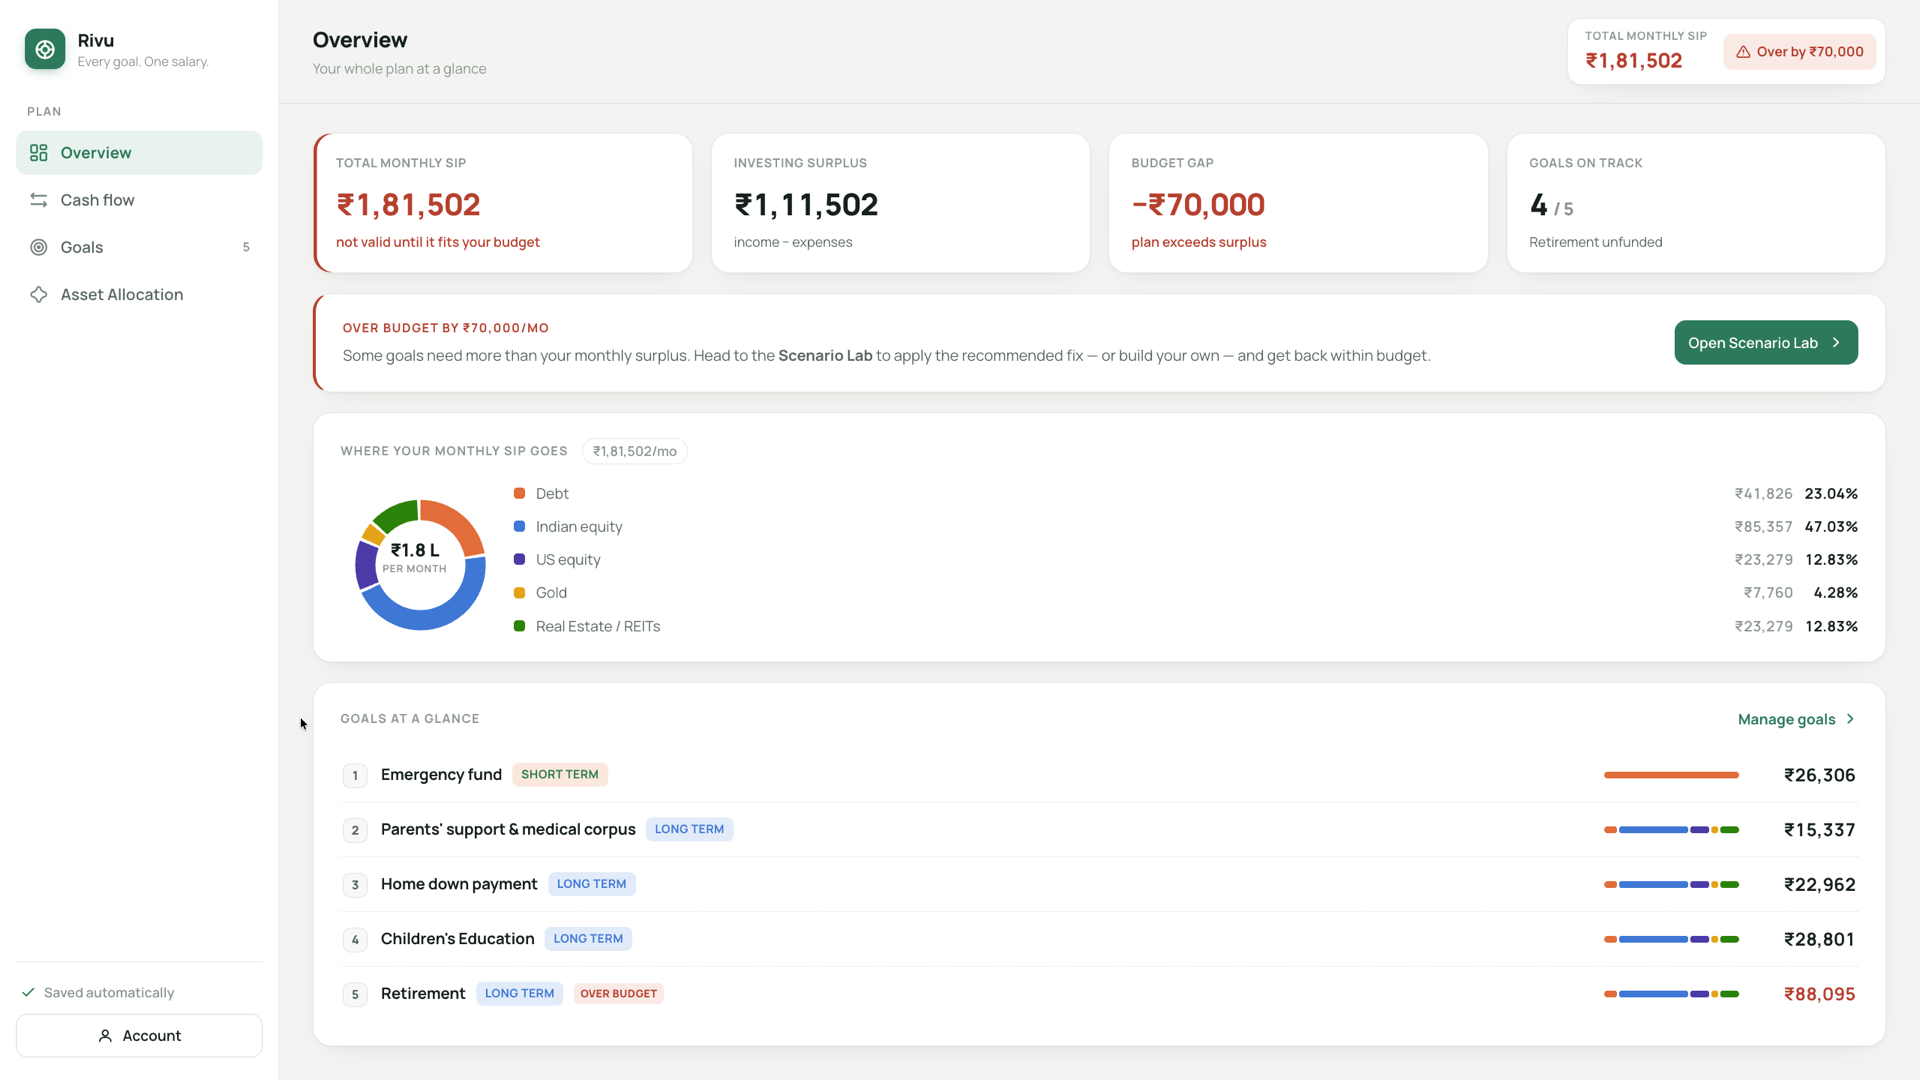
What all your goals need, added together
✕
✓
Whether that fits the money you actually have
✕
✓
Exactly what to change if it doesn't
✕
✓
Groww, ET Money and Kuvera are good at buying funds. None of them was built to check the whole plan.
The quiet part
One pot. And retirement is last in line.
Your savings aren't split up by goal. Every goal draws from the same pot — in the order it arrives.
What's left in the pot
2028after the emergency fund
2034after the house
2036after your parents
2041after the children
2054left for retirement
Nobody chose this order. It's just the order life arrives in.
You can borrow for a house. You can borrow for a degree. Nobody lends for retirement.
A gap is not a verdict
Every gap has a way out.
Most plans don't fit on the first run. That's normal, not a failure. The number never turns up alone — it comes with a list of things you could change, and you pick which one.
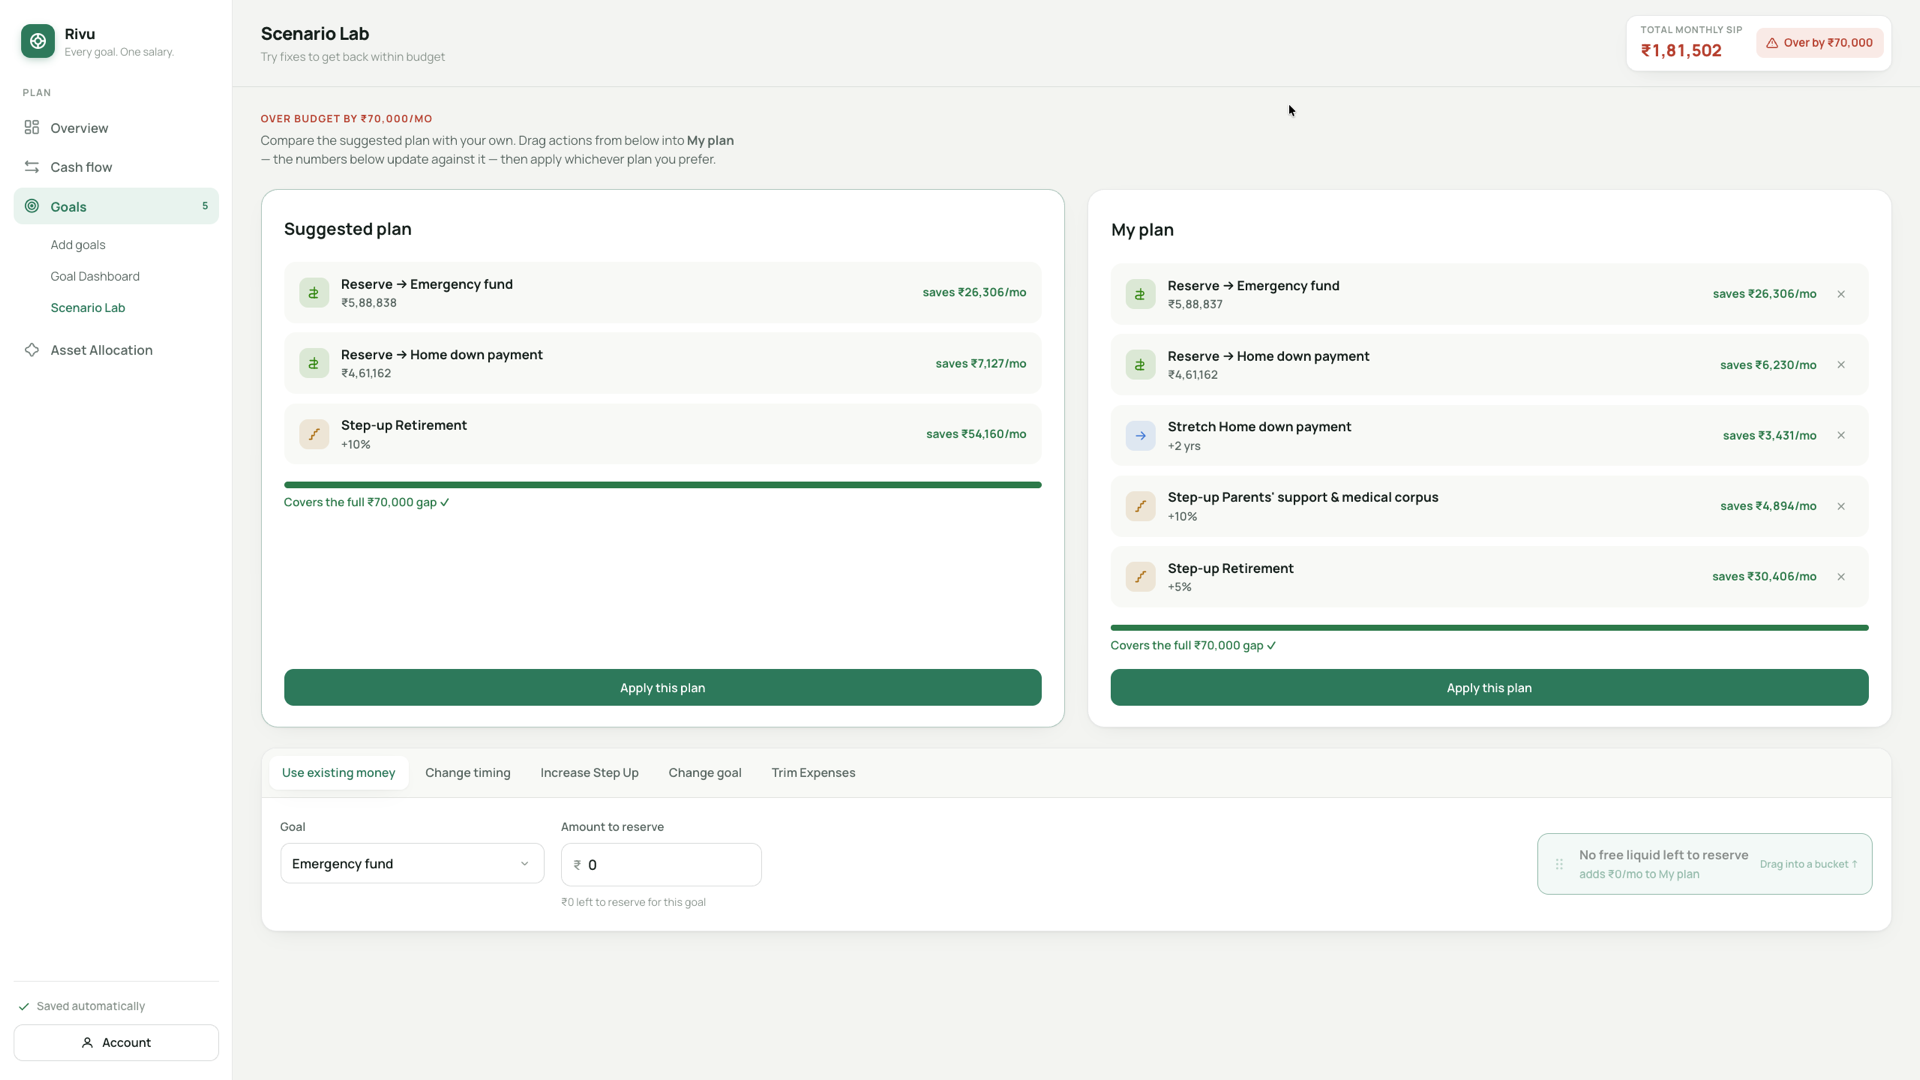
Rivu's suggestion Three moves that close Person B's ₹70,000 — without cutting a single expense or moving a single date. Untick anything you wouldn't do.
Scenario LabUntick what you won't do · tick something else instead
Still to findCovered
Other moves you could use instead
This plan closes the ₹70,000 without cutting a single expense. Untick one and swap in something else.
Dozens of plans close ₹70,000. Only one of them suits you.
Person B wouldn't commit to raising his retirement SIP 10% every year. So he took half that, put his parents' fund on a step-up instead, and pushed the house back two years. Same gap, closed. Completely different life. You pick which goal bends — not us.
That was someone else’s ₹70,000.
Yours might be smaller. It might not. Ten minutes tells you.
Ten minutes, end to end. There's no free trial — so here is every screen, before you pay a rupee.
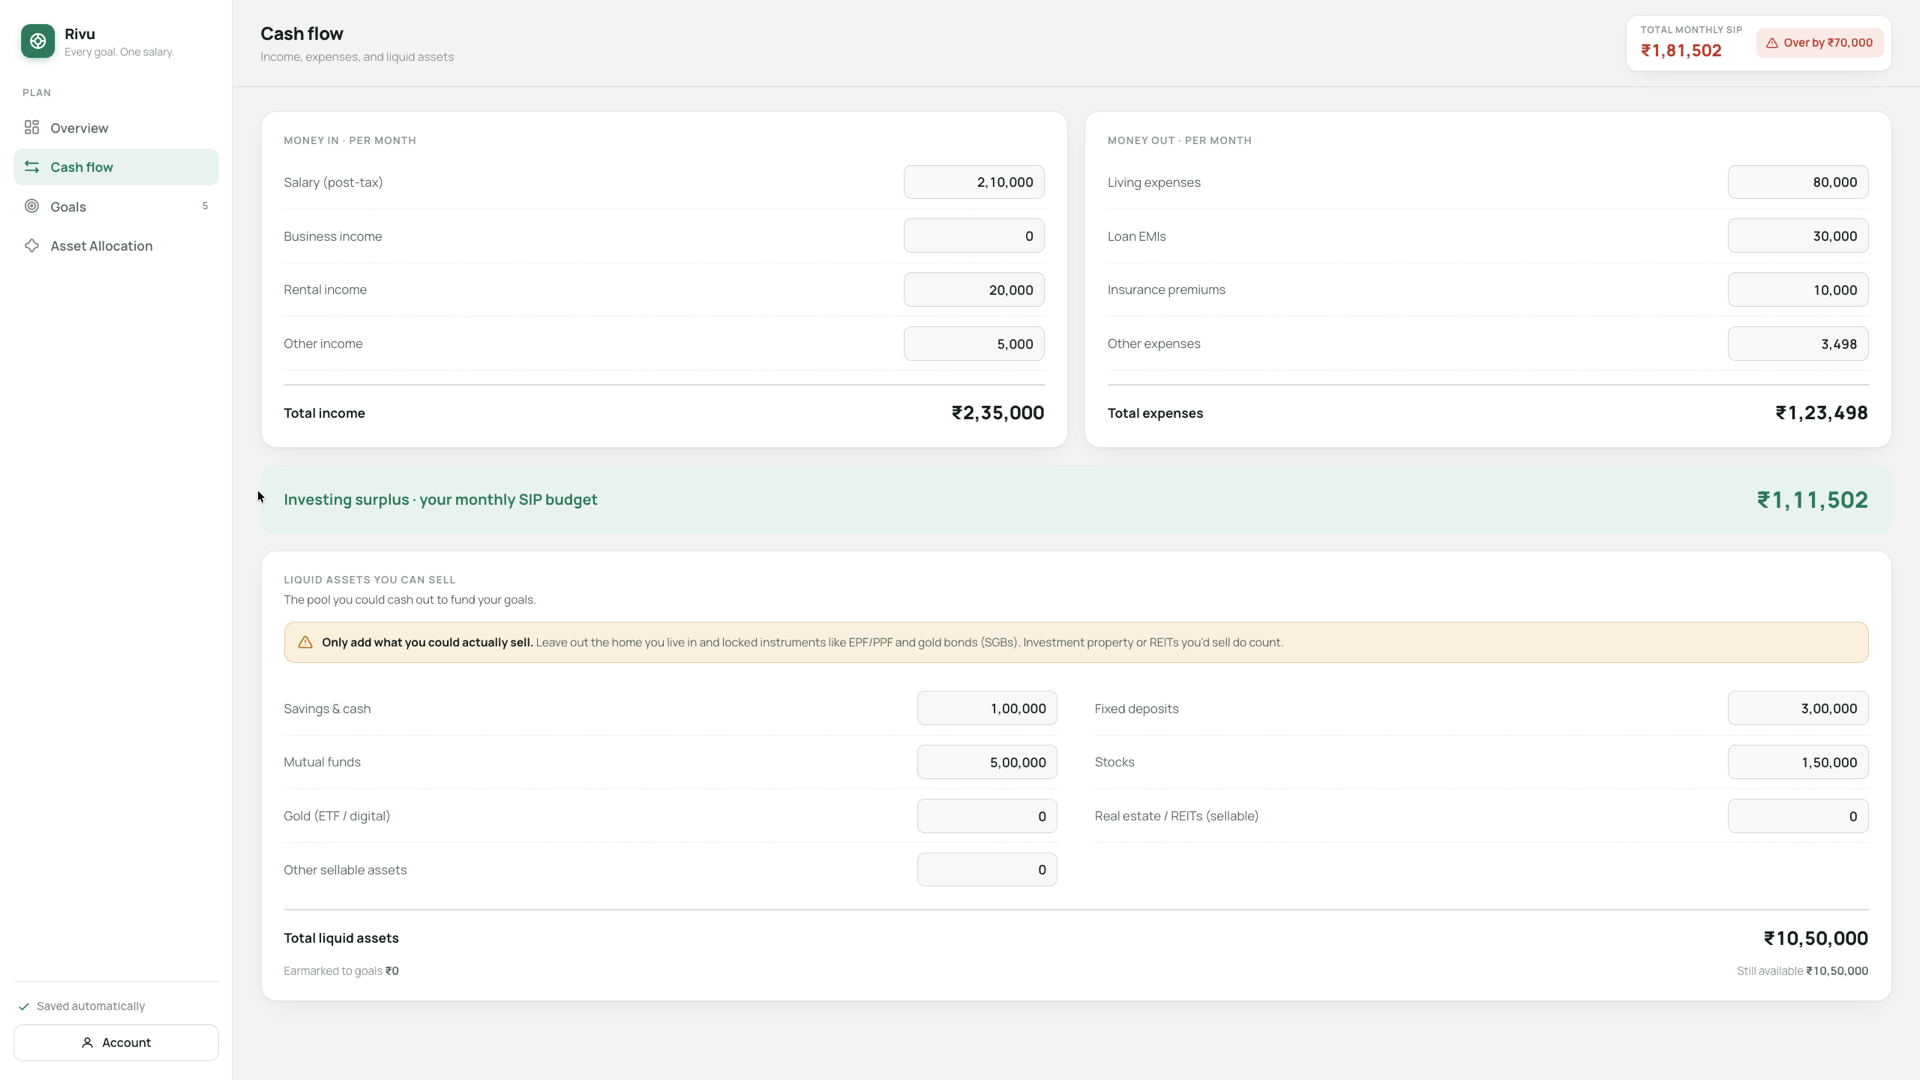
What comes in. What goes out. What's left is your real budget — not your salary. Add what you could sell too, because idle cash can do some of the work.
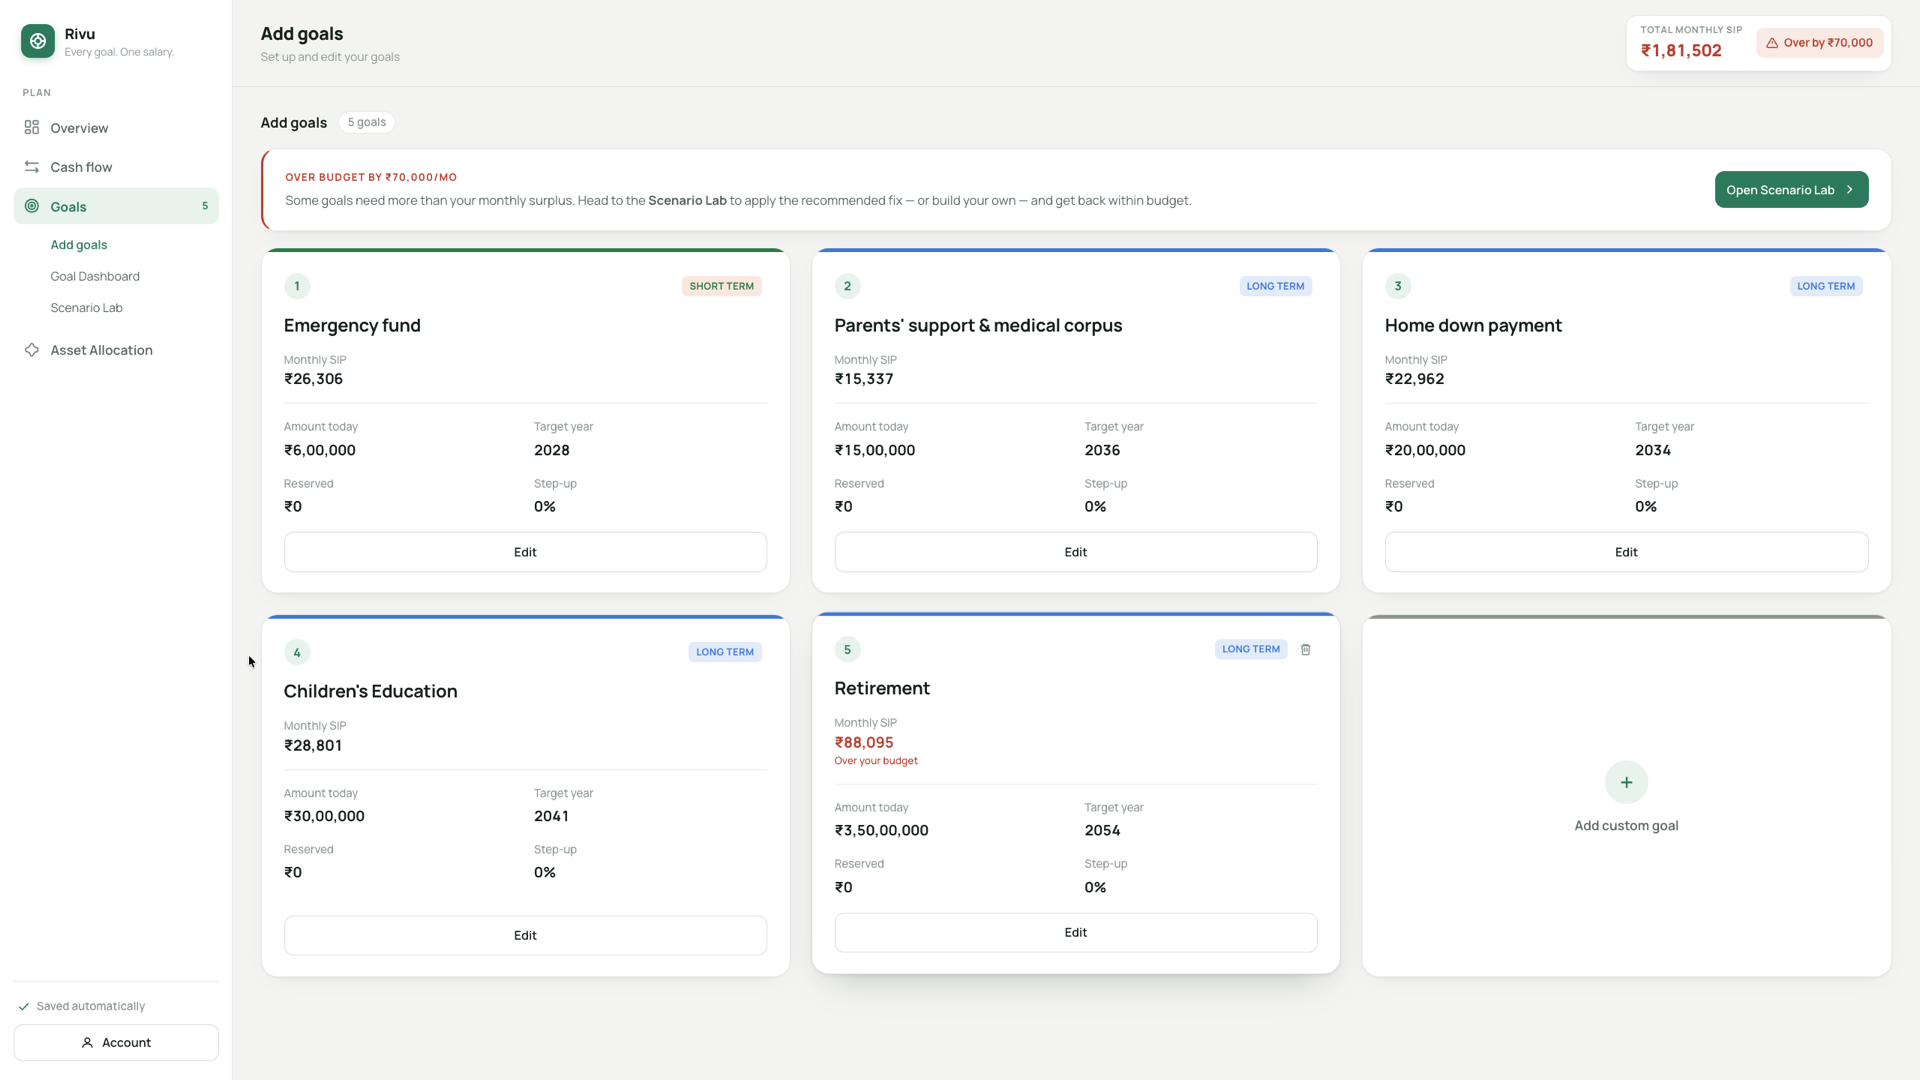
Add each goal: what it would cost today, and the year you need it. Rivu handles the inflation, and picks the right mix for how far away it is.
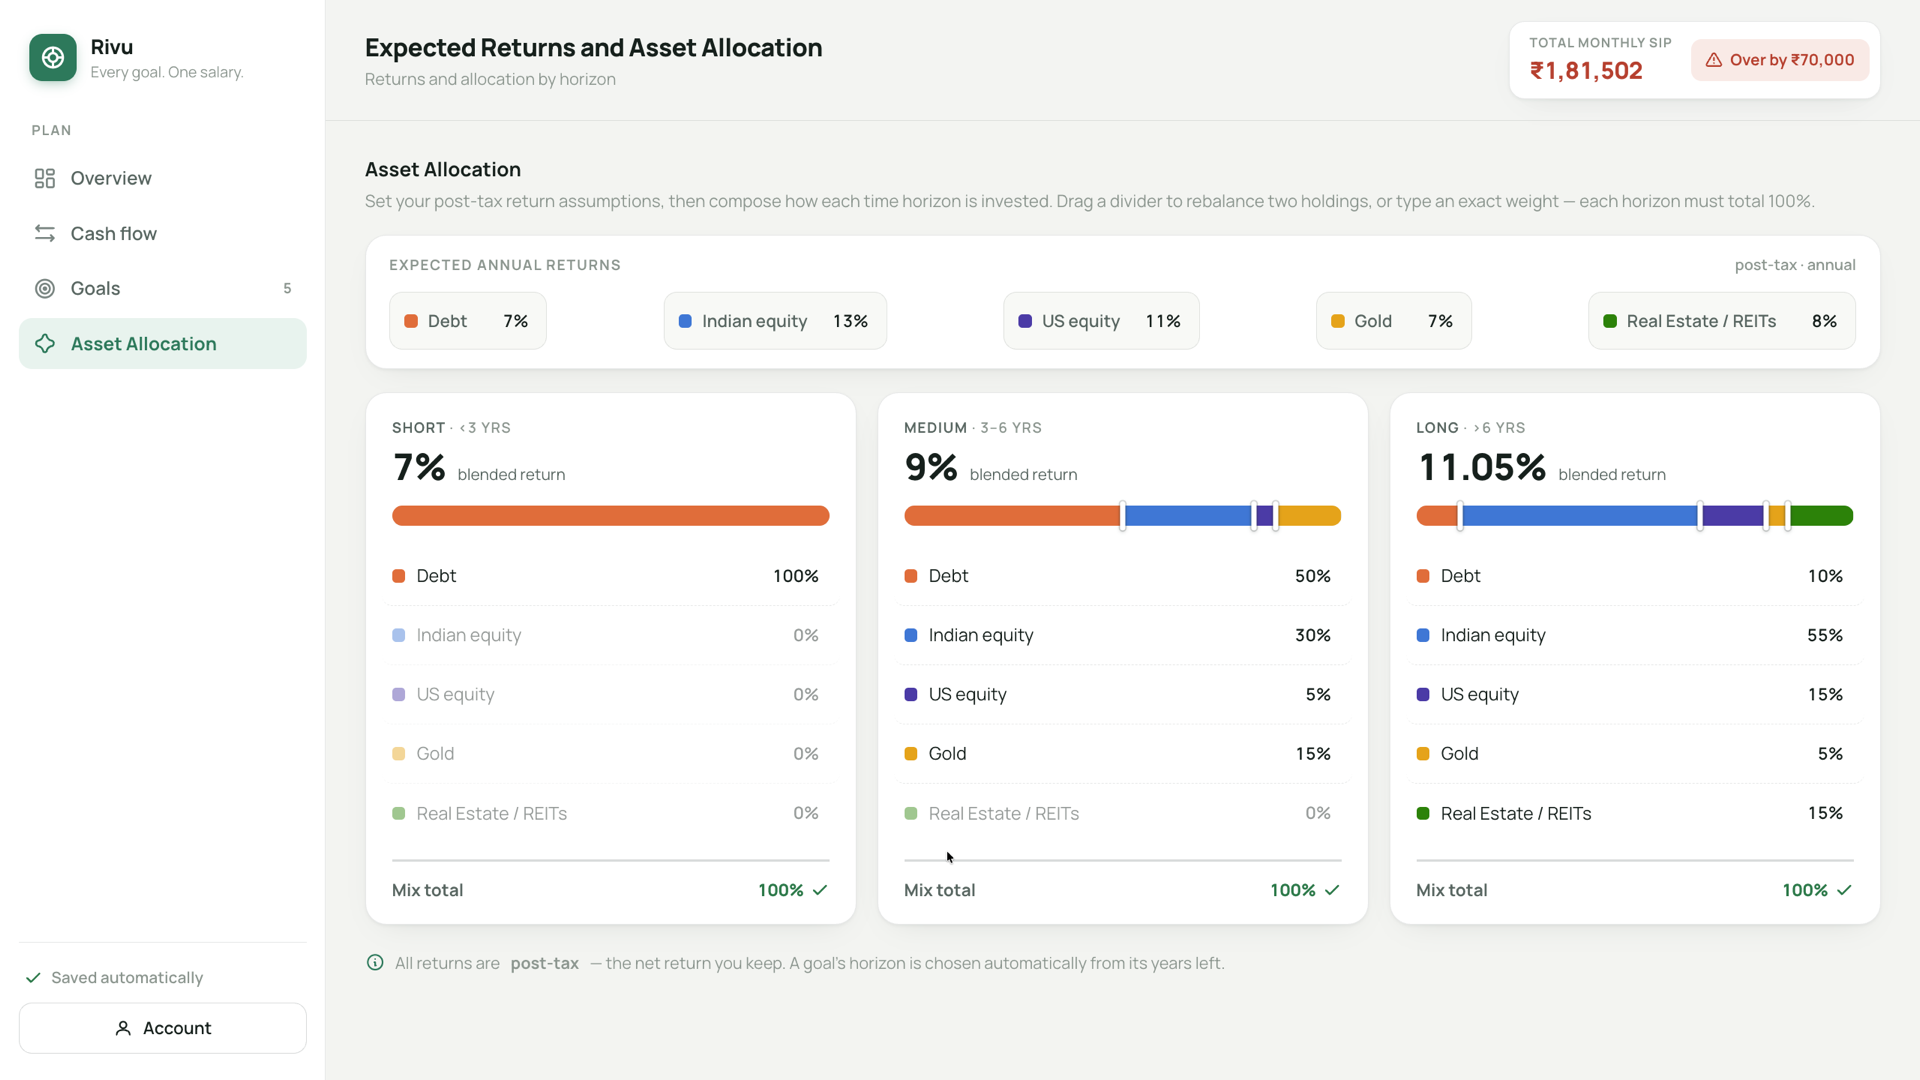
Pick your own expected returns. Decide how money for 2 years is invested versus money for 28. These are your assumptions — Rivu never tells you what to buy. Change 13% to 10% and every number after this moves.
One number for everything you want, next to the money you really have. Then that total split across assets — using the mix you set on the last screen, not one we picked for you.
A suggested fix on the left. Yours on the right. Drag in what you'd accept, throw out what you wouldn't, watch the gap close.
Ten minutes from now
Nothing about your money changes. Everything about knowing does.
Today
After
"Am I okay?" — a feeling you push away
One number, on one page
Retirement quietly takes the hit
Retirement has a number of its own
Five apps, five answers, no total
One monthly total, split by the asset mix you chose
Big decisions argued in circles
Change one input, see what it costs
"We're managing" — and neither of you believes it
A one-page plan you can hand to your spouse
The number is useful. Not carrying it alone is better.
The price
₹1,499. Paid once.
Not monthly. Re-run it as often as you like, forever.
₹1,499₹2,499one-time
Every goal priced, added up, checked against your real spare money
Your monthly investment total split across assets, using your own mix — never our advice
The Scenario Lab, to test fixes until one feels right
Unlimited re-runs. Your salary changes, so does the answer
Export your plan, or download it as a one-page PDF
No PAN, no bank login, no data on our servers
What this maths normally costs
A fee-only planner, one plan₹15,000–₹50,000
Same planner again next yearPay again
Rivu, one payment₹1,499
Rivu, re-run whenever life changesIncluded
A planner's document is right on the day you get it. Then you get a raise, the fees go up, and it isn't. Rivu takes nothing from your investments — no commission, no cut. That's why it asks you directly.
10 minutes · pay once · desktop browser · price rises to ₹2,499
Straight answers
Before you decide
Can't I just do this in Excel?
Yes. It takes an afternoon.
Then your salary changes, or the school fee goes up, and it takes another afternoon. That second one never gets done. And testing eight different fixes by hand isn't really possible at all.
What if the answer is bad?
It usually is on the first run. Most plans don't fit.
But it never comes alone. You get a list of fixes, each with a rupee figure, and you choose. Person B's ₹70,000 closed without cutting one expense.
And sometimes the answer is simply that you're already fine. That's worth knowing too.
Is this financial advice?
No. It's arithmetic on numbers you type in, using assumptions you can change.
No fund tips. No telling you which goal to drop. Not a substitute for a SEBI-registered adviser.
Where does my data go?
Nowhere. It stays in your browser. We can't see it.
Clearing your browser wipes it, so export your plan after the first run — one file, saves anywhere, opens on any machine. You can also download a one-page PDF.
How long does it take?
About 10 minutes, if you roughly know what you spend and what you've saved. A few minutes to re-run it later.
Does it work on my phone?
Not really. Use a laptop — there's a lot on screen at once. The PDF reads fine anywhere afterwards.
Who's behind it?
No expert, on purpose. Every other tool comes with someone whose income depends on what they tell you.
Rivu takes nothing from your investments, so there's no opinion of ours to trust — only maths you can check. Every assumption is yours to change.
A free 13-page guide. With a calculator and about 30 minutes, find out whether all your goals actually fit inside what you earn — the arithmetic a fee-only planner charges ₹15,000–₹50,000 to run.